Freight Brokers' Liability & Contingent Cargo Insurance
Built for freight brokers and freight forwarders that coordinate transportation but do not operate the contracted trucks. Protect the brokerage when a carrier's coverage does not respond - and address the broker's own professional and legal-liability exposures.
No driver or vehicle schedules for broker-only and forwarder-only operations.
of U.S. domestic freight tonnage moved by truck in 2024
tons of freight transported by trucks in 2024
estimated 2024 U.S. trucking freight revenue
Source: American Trucking Associations, 2024 industry estimates.
Coverage built around the broker's role
A coordinated protection package
A carrier's policy protects the carrier. A freight broker needs coverage written for the broker's contractual, professional, cargo, and vicarious-liability exposures.
Designed for allegations that the broker is legally responsible for bodily injury or property damage involving a contracted motor carrier.
A secondary layer for certain auto-liability situations when a contracted carrier's insurance does not respond as expected.
Helps address covered cargo loss or damage when the hired carrier's primary cargo policy fails, is denied, or is inadequate.
Professional liability protection for alleged mistakes, omissions, miscommunication, or failure to perform brokerage services.
Premises and operations protection for third-party bodily injury, property damage, and other covered general-liability claims.
The $75,000 surety bond or trust-fund requirement is distinct from cargo, auto, E&O, and general-liability insurance.
Availability, limits, defense provisions, exclusions, deductibles, and terms vary by carrier and policy form.
The contingent cargo safety net
When the hired carrier's policy does not respond
The shipper expects the broker to coordinate a reliable move. If cargo is lost or damaged, the carrier's insurer may deny the claim, apply an exclusion, find that coverage lapsed, or pay only up to a limited amount. A properly structured contingent cargo policy can help protect the broker from a covered gap.
- Carrier cargo coverage is cancelled, lapsed, or otherwise unavailable
- A policy exclusion conflicts with the commodity or cause of loss
- The carrier's available limit is less than the covered shipment value
- A subcontracted carrier creates an unexpected coverage problem
How a broker-focused program works
Primary carrier insurance first. Broker protection behind it.
Vet the carrier
Confirm active authority, safety information, insurance dates, limits, commodities, and any required endorsements before tendering the load.
Document the move
Keep the broker-carrier agreement, certificate, load confirmation, shipper contract, bill of lading, and communication trail.
Respond to a covered gap
If the primary carrier coverage does not respond, report the matter promptly so the contingent or broker-liability policy can be evaluated.
Carrier vetting and negligent-selection defense
Underwriters want to understand how carriers enter - and stay on - your panel
The uploaded brokerage applications consistently ask about carrier selection, written agreements, insurance verification, authority monitoring, safety records, re-vetting frequency, exceptions, and record retention. Those controls can materially affect eligibility and terms.
Freight forwarders and multimodal movements
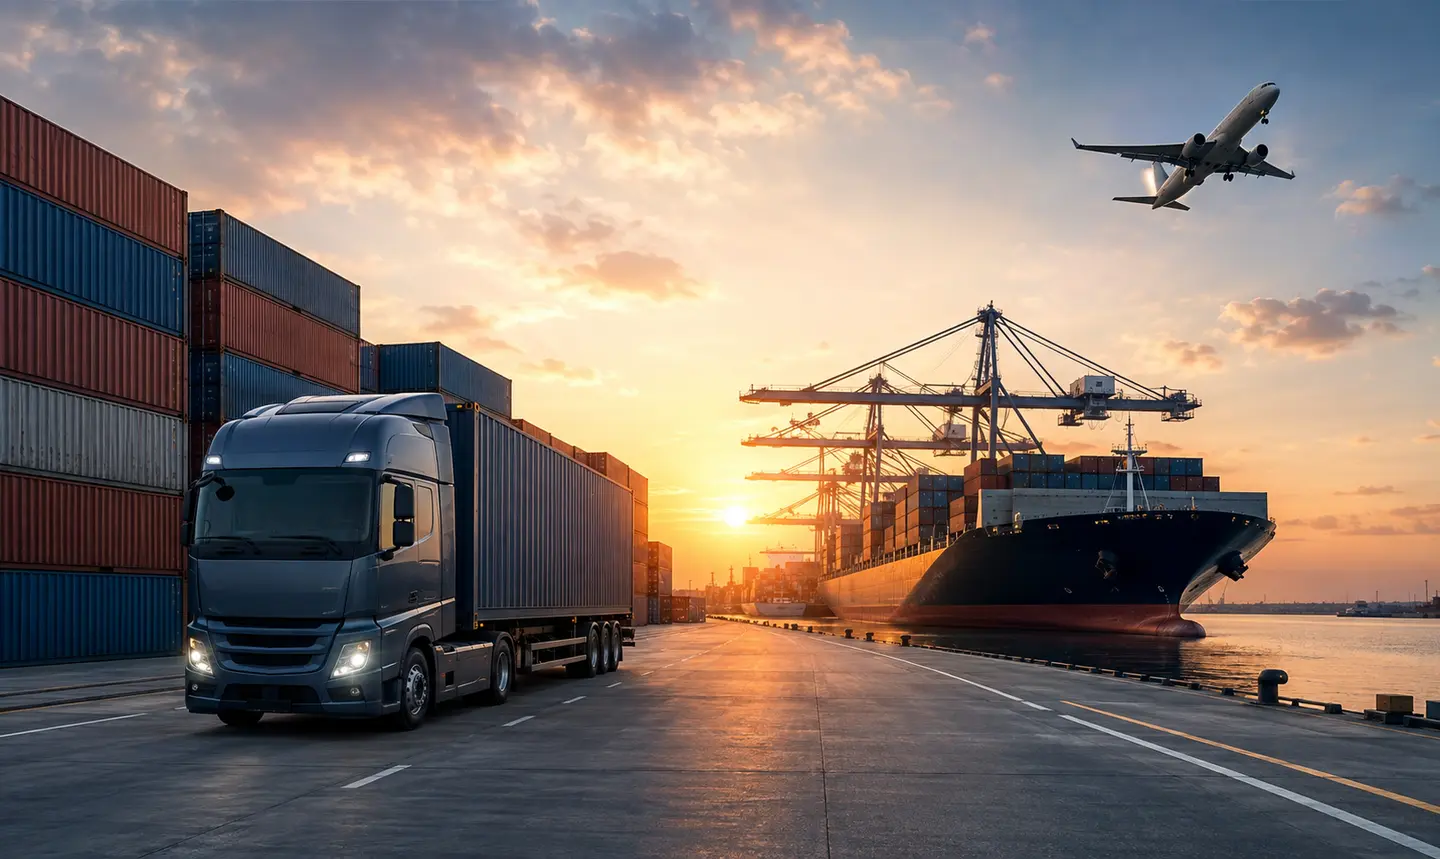
Coverage should match how the shipment actually moves
Domestic freight forwarders may arrange truck, rail, air, ocean, or combined movements and can assume responsibilities beyond a property broker's role. Tell the underwriter whether your company issues bills of lading, consolidates freight, uses warehouses, crosses borders, or accepts contractual responsibility for cargo.
Cargo claims and contract disputes
Fast documentation helps preserve options
When cargo is damaged, preserve the shipment records, carrier insurance evidence, photos, contracts, delivery exceptions, communications, and claim correspondence. Report potential claims promptly and avoid making admissions or voluntarily assuming costs without coordinating with the appropriate insurer.
Common underwriting documents
- Broker-carrier agreement
- Shipper/customer contract
- Current policies
- Five-year loss runs
- Carrier panel or sample
- Written vetting procedures
2026 financial-responsibility update
BMC-84 and BMC-85 requirements are separate from insurance
FMCSA requires property brokers and freight forwarders subject to federal jurisdiction to maintain $75,000 in financial security. Beginning January 16, 2026, updated rules govern eligible BMC-85 trust assets and the consequences when available financial security falls below the required amount.
This is general insurance information, not legal advice. Confirm current registration and filing requirements with FMCSA and qualified counsel.
Review FMCSA's 2026 rule overview$75,000 financial security
BMC-84 surety bond or BMC-85 trust-fund filing.
Separate from liability coverage
The filing does not replace cargo, auto, E&O, or general liability insurance.
Same entity matters
Broker and forwarder authorities held by different legal entities may require separate financial security.
Frequently asked questions
Freight broker insurance answers
What is contingent cargo insurance for a freight broker?
Contingent cargo insurance can provide a secondary layer of protection when a contracted motor carrier's cargo policy does not respond to an otherwise covered loss. The exact trigger, exclusions, valuation method, and limits depend on the policy.
Is contingent cargo the same as motor truck cargo insurance?
No. Motor truck cargo is generally written for the motor carrier physically transporting property. Contingent cargo is designed for brokerage or forwarding exposures and should not be presented as a replacement for the contracted carrier's primary cargo coverage.
What does freight broker auto liability address?
Freight broker auto liability is intended to address the broker's alleged legal liability arising from the use of contracted motor carriers. Coverage wording varies, so defense provisions, exclusions, limits, and any aggregate must be reviewed in the actual quote and policy.
Do freight brokers need a BMC-84 or BMC-85 filing?
FMCSA requires brokers and freight forwarders subject to its jurisdiction to maintain $75,000 in financial responsibility through a BMC-84 surety bond or BMC-85 trust fund filing. This financial security is separate from liability and cargo insurance.
What information is needed to request a quote?
The short application asks for company and contact information, authority type, MC or FF number if assigned, annual freight receipts, estimated shipments, commodities, operating territory, requested coverages, carrier-vetting confirmations, and five-year loss history.
Does the freight broker form require drivers or vehicles?
No. The dedicated form is for freight brokers and freight forwarders that do not operate vehicles. A business that also operates trucks should complete the motor-carrier application so driver and vehicle exposures can be reviewed.