Transportation and passenger services
- Courier services
- Freight forwarders
- Moving services
- Pilot cars
- Taxi and limo services
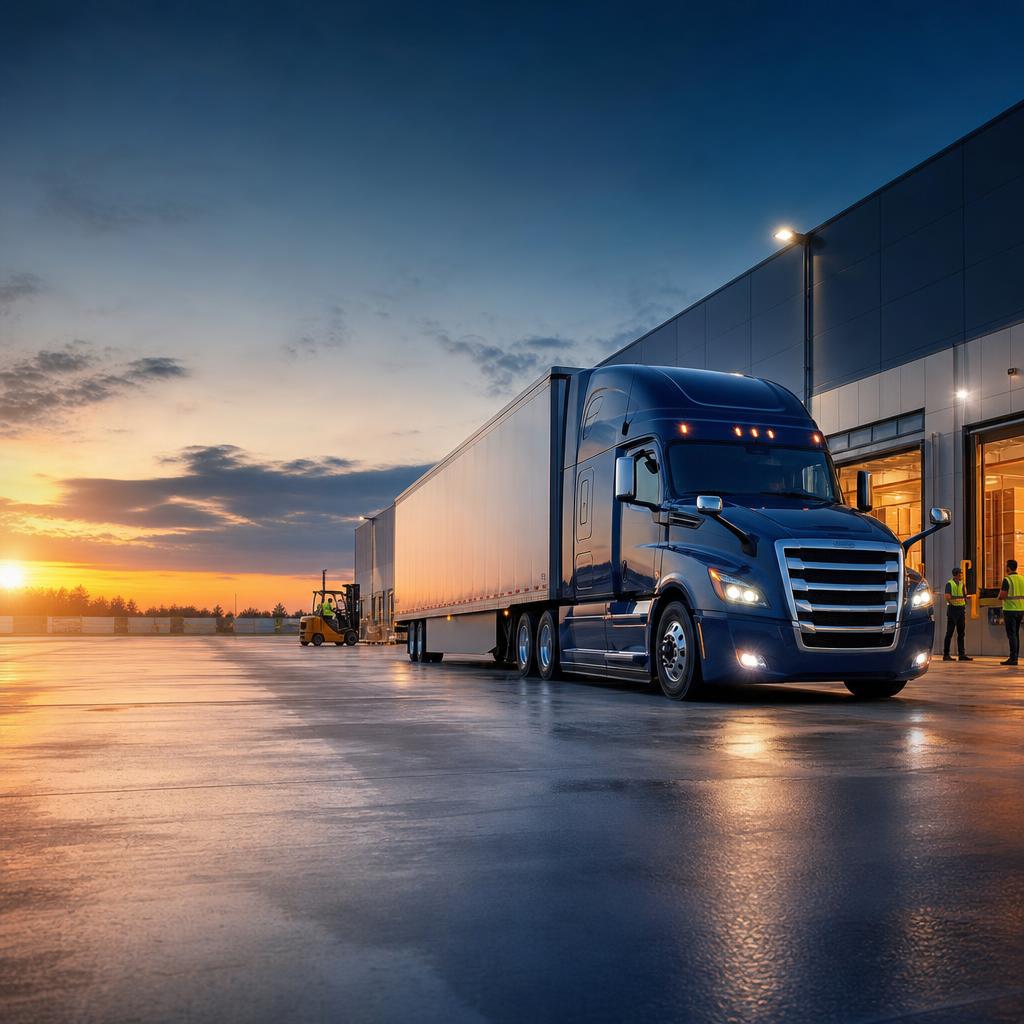
Explore Truckers General Liability options for the terminals, contracts, loading activity, and business operations surrounding your fleet.
Some of the insurance markets we work with
Carrier availability varies by state, operation type, fleet size, and underwriting requirements.
Truckers General Liability (TGL) is a General Liability discussion tailored to the business activities that surround a motor carrier. Terminals, loading and unloading, contracts, customers, and dispatch operations may create exposures that are different from driving a covered vehicle.
Commercial auto liability and General Liability can apply to different situations. Depending on the policy language and facts of a loss, Truckers GL may be relevant to premises incidents, certain loading activity, and other business operations.
May address certain covered injuries at terminals, offices, and facilities
May address certain covered claims arising from described trucking activities
May be relevant for eligible product-related exposures, subject to policy terms
May be relevant to qualifying work after delivery or services are completed
May address certain covered personal or advertising injury allegations
May be available for eligible medical-payment coverage, subject to the form
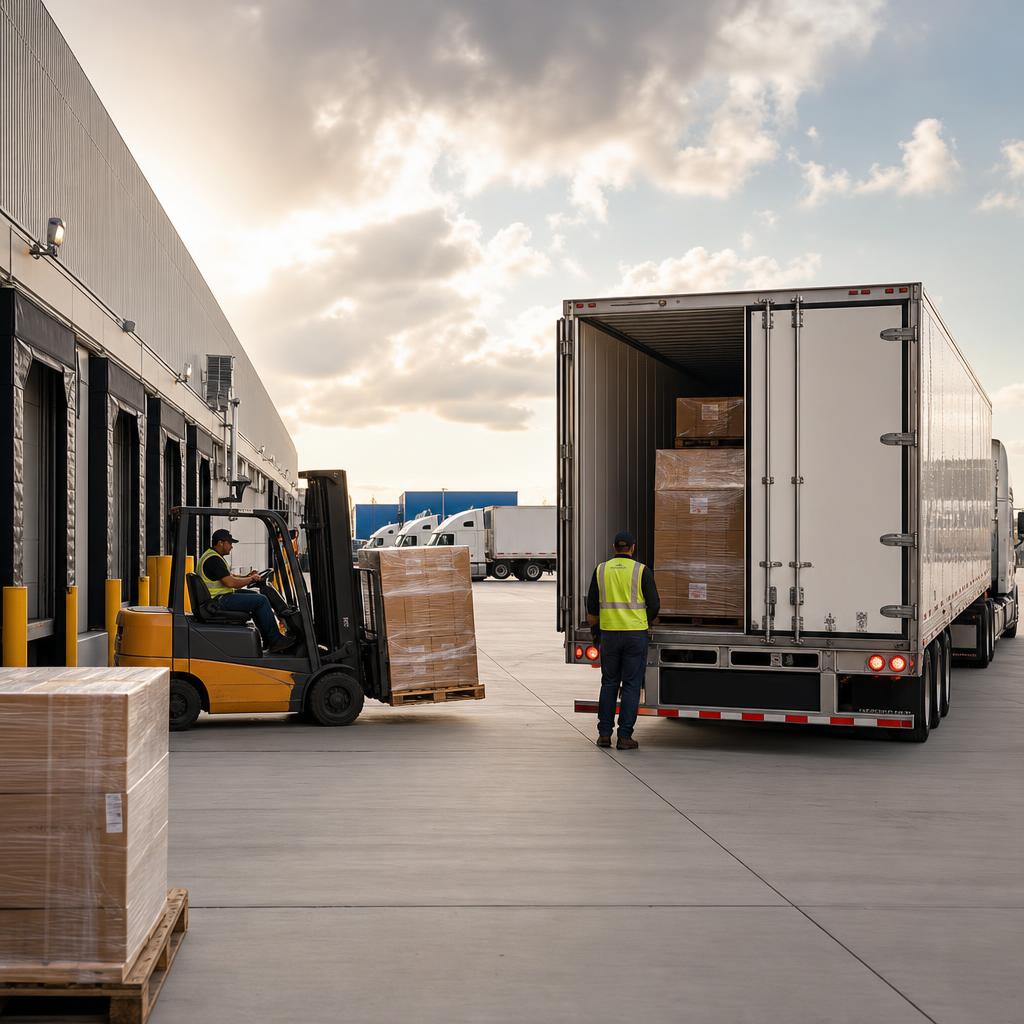
A warehouse worker is injured while helping load freight. Depending on the circumstances and policy terms, this type of incident may be reported for evaluation.
During terminal operations, equipment damages a shipper's goods. The facts, contract, and policy language help determine which coverage should evaluate the report.
A customer slips at a dispatch office. Depending on the circumstances and policy terms, this type of premises incident may be reported for evaluation.
These are supplied program guidelines, not a quote or an availability promise. Final terms are subject to underwriting and the policy issued.
For eligible operations, supplied guidelines indicate excess auto liability may be available alongside the primary General Liability submission. Terms and availability are subject to underwriting.
Coverage form, attachment, limits, deductibles, and availability are determined by the carrier underwriting review and issued policy.
Start with your operations, locations, contracts, and insurance history. A coverage review can help identify available Truckers GL pathways.
Who may need a review
A useful review looks at the people, facilities, contracts, and services surrounding the transportation operation—not only the miles driven. The activities below may create business exposures worth discussing.
Contracts and operations
Terminals, customer sites, loading and unloading activity, warehouses, and service agreements can all shape the questions asked in a trucking General Liability submission.
Review service agreements, lease terms, and certificate requests before work begins. They may request specific limits, additional insured status, or other requirements that must be evaluated against the available policy terms.
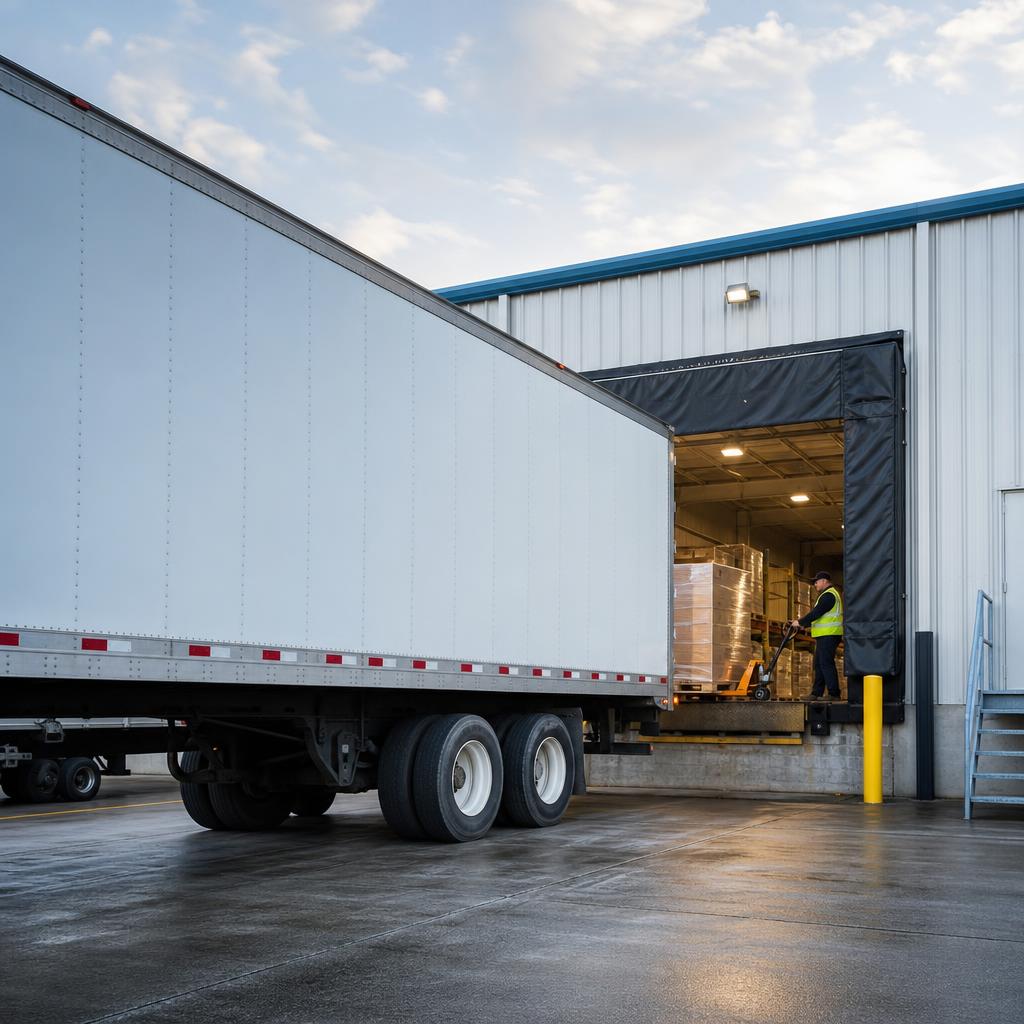
Explain where work happens, who handles freight, what employees or subcontractors do, and how customers access the site. These operational details help frame potential premises and operations exposures.
Claims readiness
Organized reporting and records do not change policy terms, but they can help your team provide the information needed to evaluate a reported claim.
Prioritize safety, secure the location, and follow the operation’s emergency procedures.
Record the date, location, involved parties, photos, witnesses, and relevant contract or delivery details.
Notify the claim contact shown on the policy and follow carrier reporting instructions promptly.
Preserve dispatch, training, maintenance, terminal, and communication records that may relate to the event.
Premises and operations
A terminal, warehouse, dispatch office, cross-dock, or customer-facing location can change the exposure picture. Keep a current account of your locations, visitors, services, and loss controls.
Market and program access
Carrier and program options depend on the operation, territory, services, prior experience, contracts, and underwriting review. Potential pathways may include:
Program guideline
Eligible transportation operations may be considered. The following supplied parameters are program guidelines, not a quote or availability promise:
Potential market access is evaluated with the complete submission and underwriting review.
Potential market access is evaluated with the complete submission and underwriting review.
Potential market access is evaluated with the complete submission and underwriting review.
General Liability questions
A complete description of the operation helps the discussion start with the right questions.
Start a General Liability reviewCommercial auto liability is generally centered on the use of covered vehicles. General Liability is designed for many non-driving business exposures, such as premises, operations, completed work, or advertising injury. The specific division between policies depends on the facts and policy language.
Often. A shipper, warehouse, terminal, landlord, or customer agreement may require a certificate, an additional insured endorsement, a specific limit, or other terms. Bring the contract to the review so the requested wording can be considered before a job begins.
Some programs may consider new ventures, but requirements, documentation, pricing, and availability vary. A clear description of the operation, drivers, locations, contracts, and prior experience helps make the first review more useful.
These are different policy structures that can affect when coverage may respond. A coverage professional can help explain the form offered, applicable retroactive dates or reporting provisions, and how the terms fit the operation.