Intermodal container truck at port terminal
    UIIA-Registered Agency

    Intermodal Insurance in Fontana, CA

    UIIA-Compliant Coverage for Container & Chassis Carriers

    Fontana sits at the geographic center of the Inland Empire — the largest inland distribution market in the United States, encompassing one of the largest concentrations of industrial and warehouse space in the country across San Bernardino and Riverside counties. Carriers here move ocean containers from the Ports of Los Angeles and Long Beach through BNSF San Bernardino and UP's Inland Empire Intermodal Terminal (West Colton) to warehouses spanning Fontana, Rialto, Ontario, San Bernardino, and Riverside. A standard commercial auto policy doesn't cover the UIIA chassis interchange requirements, trailer interchange agreements, and high-volume port exposure that define intermodal work in this market. You need a policy structured for container drayage — with the right endorsements, the right limits, and a UIIA certificate filed before you pull your first box.

    Same-Day Quotes Same-Day COIs UIIA Support Nationwide

    Same-day UIIA filings.

    Some of the insurance markets we work with

    Berkshire Hathaway Homestate Companies
    National Indemnity Company
    GEICO
    Lloyd's of London
    Everspan Group
    Berkley Small Business Solutions
    Northland Insurance
    Canal Insurance
    Applied Underwriters
    Crum & Forster
    IAT Insurance Group
    Carolina Casualty

    Carrier availability varies by state, operation type, fleet size, and underwriting requirements.

    Step 1 of 2 — Quick Info

    GET YOUR FREE QUOTE NOW

    No commitment required · Takes 2 minutes

    Your information is secure and never shared. We use it only to prepare your quote.

    No commitment required · Takes 2 minutes · By continuing, you consent to being contacted about your quote. Privacy Policy

    UIIA-Registered Agency
    Same-Day COI Filings
    E&S Market Access
    IANA Filing Approved
    25+ Years Experience
    Required Before You Pull a Container

    UIIA Insurance Requirements

    Every carrier pulling ocean or rail containers must meet UIIA minimums. Most retail agents get these wrong — here's what you actually need.

    $1,000,000 CSL
    Auto Liability

    Must be Any Auto, Scheduled & Hired, or All Owned & Hired. FMCSA's $750K is NOT enough.

    $1M / $2M
    General Liability

    $1M per occurrence, $2M aggregate. Most EPs require additional-insured endorsement.

    $20K – $50K
    Trailer Interchange

    Covers non-owned chassis in your care. Must include comp, collision, fire & theft.

    $100,000+
    Motor Truck Cargo

    Most EPs require $100K minimum; some require up to $500K depending on freight.

    Also required: UIIE-1 endorsement on your auto policy and CA23-17 or TE23-17B on your cargo policy. Workers' comp required if your state mandates it or your equipment provider requires it. View official UIIA requirements

    Who Needs Intermodal Insurance?

    If you pull containers from ports or rail yards, you need UIIA-compliant coverage.

    Port drayage trucks at terminal

    Port Drayage Carriers

    • Move containers from ocean terminals
    • Pull UIIA-controlled chassis
    • Need UIIA cert filed with IANA
    • LA, Long Beach, Houston, Savannah, NJ
    Intermodal truck at rail yard

    Rail Ramp Drayage

    • Serve BNSF, UP, CSX, NS, CPKC ramps
    • Pull inland intermodal containers
    • Chicago, Dallas, Memphis, KC hubs
    • Must meet same UIIA minimums
    Owner operator intermodal truck

    Owner-Operators

    • Leased to drayage companies
    • Running under your own authority
    • Need your own UIIA-compliant policy
    • We write O/O intermodal coverage
    BNSF San Bernardino intermodal ramp — primary IE rail gateway
    UP Inland Empire Intermodal Terminal (West Colton) — eastern IE container service
    POLA/POLB drayage to Fontana, Rialto, Ontario, and San Bernardino DCs
    I-10 / I-15 corridor coverage — two of California's highest-volume freight routes
    UIIA Certificate of Insurance filing assistance for carriers with intermodal equipment agreements
    UIIA chassis interchange and trailer interchange coverage included
    E&S markets experienced with high-frequency Inland Empire container operations

    Coverage Built for Fontana Carriers

    We write full-stack intermodal programs — not just a basic truck policy with a container checkbox.

    Auto Liability

    Core liability protection when your trucks move containers between LA/Long Beach port terminals, BNSF San Bernardino, UP Inland Empire Intermodal Terminal (West Colton), and Inland Empire warehouse customers on the I-10 and I-15 corridors.

    Physical Damage

    Covers collision and comprehensive losses to your tractors on high-traffic Inland Empire port and rail routes, including damage in yard environments at BNSF San Bernardino and UP Inland Empire Intermodal Terminal (West Colton).

    Motor Truck Cargo

    Protects freight inside containers while in your care between POLA/POLB terminals, Inland Empire rail ramps, and the dense Fontana–San Bernardino warehouse market.

    Trailer Interchange Coverage

    Covers physical damage to non-owned trailers and containers you pull under UIIA or written interchange agreements at LA/LB terminals and Inland Empire rail facilities.

    Chassis Coverage

    Insures chassis you lease or borrow from POLA, POLB, or Inland Empire rail pool providers while they're in your care, custody, and control.

    General Liability

    Protects your business from certain third-party injury or property damage claims outside of the covered auto — including yard and terminal-related exposures common in Inland Empire distribution environments.

    Excess Liability / Umbrella

    Adds higher limits above your primary policy to meet requirements from railroads, steamship lines, large brokers, and 3PLs operating in the Inland Empire market.

    Non-Trucking (Bobtail) Liability

    Available when your tractors are operated off dispatch or bobtailing between the Fontana area, rail ramps, and LA/LB terminals without a trailer attached.

    Same-Day UIIA Filings

    From Quote to Pulling Containers — Same Day

    01

    Get a Quote

    Tell us your operation — trucks, equipment providers, routes. We structure the right program.

    02

    Bind Coverage

    Review your policy. We confirm UIIA endorsements are correct.

    03

    We File Your UIIA COI

    Truxsurance files your Certificate of Insurance with IANA the same business day you bind.

    04

    Start Pulling Containers

    IANA verifies your filing. Your UIIA status activates. You're cleared to haul.

    Drayage driver at port terminal
    Local Freight Market

    The Fontana Intermodal Market

    The Inland Empire is the largest inland distribution market in the United States, with an extensive concentration of warehouse and distribution space across San Bernardino and Riverside counties — a market that industry sources consistently rank above any comparable inland distribution region in the United States. Fontana occupies the critical I-10 / I-15 interchange — the point where two of Southern California's most important freight corridors converge — placing it within 60 miles of the Ports of Los Angeles and Long Beach and within a few miles of BNSF San Bernardino, the primary intermodal rail ramp serving the eastern Inland Empire. Union Pacific's Inland Empire Intermodal Terminal (IEIT) at West Colton sits roughly five miles west of San Bernardino and handles UP-routed containers moving between the ports and inland customers. Together, these two facilities support tens of thousands of container lifts annually serving the dense cluster of big-box retailers, e-commerce fulfillment centers, and third-party logistics providers in Fontana, Rialto, Ontario, and San Bernardino. The market operates virtually around the clock, with drayage carriers running multiple turns per day between port terminals and nearby DCs. Ontario International Airport and the growing CA-60 and CA-71 connection corridors add additional freight volume to an already saturated road network.

    Operations

    How Intermodal Works Here

    Inland Empire carriers typically handle one or more of four intermodal operation types. Port drayage moves containers from POLA or POLB terminals to Inland Empire warehouses and distribution centers — the highest-volume movement in the market. Rail pickup-and-delivery (P&D) moves containers between BNSF San Bernardino or UP Inland Empire Intermodal Terminal (West Colton) and customers who don't receive direct port drayage. Repositioning moves empty containers and chassis between facilities, terminals, and pool locations. Bobtail operations — tractor moves without a trailer, common between the Fontana area, port terminals, and rail ramps — present their own liability exposure. Each operation type requires specific insurance endorsements. UIIA equipment providers — BNSF, Maersk, Flexi-Van, TTSI, and others — each have specific Certificate of Insurance requirements that must be met before a carrier can pull their equipment.

    Underwriting

    What Underwriters Evaluate

    Fontana and Inland Empire intermodal accounts are typically placed through Excess & Surplus lines markets. Standard admitted carriers commonly exclude or restrict containerized freight, UIIA chassis interchange, and non-owned trailer coverage in ways that leave drayage carriers significantly underinsured. E&S underwriters evaluate the number and type of power units, owned versus leased chassis arrangements, the complete list of UIIA equipment providers, driver quality data including MVRs and prior experience, haul radius, and commodity types. IE carriers frequently haul high-value consumer electronics, retail inventory, and perishable goods — all of which can affect cargo limits, exclusions, and premium. A complete UIIA equipment provider list is essential at application; missing providers can void coverage on equipment interchange claims.

    Quote Preparation

    Documents to Have Ready

    Gathering these before you reach out speeds up the quoting and binding process significantly.

    • Completed commercial truck insurance application (ACORD 131 or equivalent)
    • Equipment schedule — all power units with VINs, years, and values
    • Driver list with CDL numbers, dates of birth, and MVR authorization
    • Complete UIIA equipment provider list (BNSF, Maersk, Flexi-Van, TTSI, etc.)
    • 3 years loss runs from current carrier and all prior carriers
    • MC/DOT authority number and current FMCSA safety rating
    • Leased chassis agreements or equipment interchange contracts (if applicable)
    • Current Certificate of Insurance if replacing an existing policy
    Container truck fleet at port

    Why Carriers Choose Truxsurance

    Most retail agents don't know the UIIA from the MCS-90. We do intermodal exclusively.

    • UIIA-registered agency — approved IANA filer
    • Same-day COI filings — start hauling today
    • E&S markets that understand container exposure
    • Coverage for all major U.S. ports & rail ramps
    • Multi-state program support where available
    • 25+ years transportation insurance experience

    Frequently Asked Questions

    Product and local operating guide

    Building a complete Fontana, CA intermodal trucking insurance submission

    An intermodal submission must describe the complete container operation: marine terminals and rail ramps served, equipment providers, UIIA status, chassis arrangements, interchange agreements, cargo custody, garaging, operating radius, drivers, and the mix of local and regional work.

    Identify each equipment provider and terminal or rail facility used, along with container volume, empty repositioning, yard moves, warehouse transfers, bonded or refrigerated freight, and conventional truckload work. Underwriters need the real operating mix rather than a generic drayage label.

    For a Fontana, CA operation, the application should state where vehicles are actually garaged, every state or corridor served, maximum and typical radius, annual mileage, commodities, revenue, vehicle values, driver experience, prior coverage, and loss history. If the business is new, include relevant ownership, driving, safety, and industry experience instead of leaving the underwriter to infer it.
    Coverage structure

    The review commonly considers primary auto liability, cargo, physical damage, truckers general liability, trailer interchange or chassis physical damage, excess liability, and any provider-specific requirements. Limits and endorsements must be checked against current agreements.

    Deductibles, sublimits, scheduled equipment, covered causes of loss, exclusions, territory, and valuation provisions should be reviewed alongside the premium. A lower indication is not equivalent if it removes a required form or leaves a material exposure uninsured.

    Contracts, filings and certificates

    UIIA registration, equipment-provider addenda, IANA filing instructions, terminal credentials, and certificate-holder wording belong in the submission file. Platform or provider acceptance is separate from underwriting and is never guaranteed by a certificate alone.

    Provide the current written requirement rather than a summary from memory. Review named insured, certificate holder, additional-insured wording, waiver requests, primary and noncontributory language, notice provisions, filings, and effective dates before accepting work.

    Claims-ready operating controls

    A strong insurance file also explains how the business prevents and responds to loss. Document driver qualification, onboarding, vehicle inspections, preventive maintenance, cargo securement, dash cameras or telematics, accident reporting, post-loss testing, cargo documentation, and escalation responsibilities.

    Keep schedules and operations current after binding. Adding vehicles, drivers, commodities, territories, contracts, equipment providers, or a different type of hauling can require carrier approval or a policy change. Report changes before the new exposure begins whenever possible.

    Original Truxsurance editorial imagery

    How the operation connects from equipment to delivery

    These original images illustrate the operating details an application should describe. They are representative—not photographs of a specific insured, terminal, railroad, port, or facility in Fontana, CA.

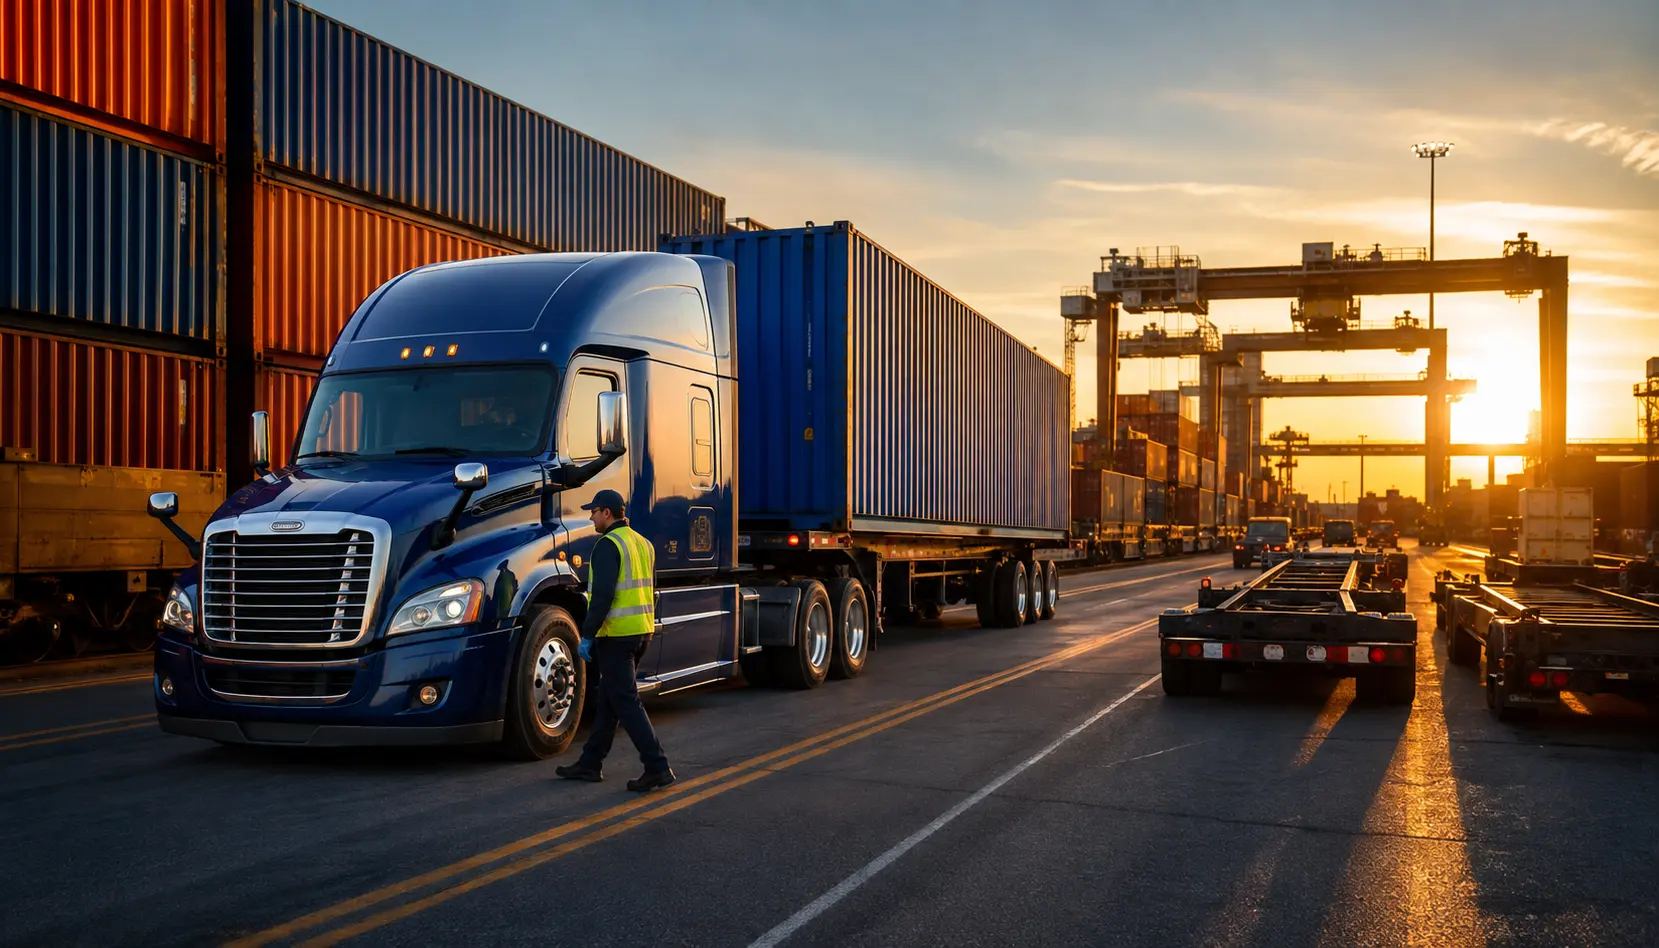
    Intermodal container truck operating beside a rail ramp

    Rail-ramp and intermodal operations

    Rail facilities, equipment providers, container custody, chassis use and interchange requirements should be identified before quoting.

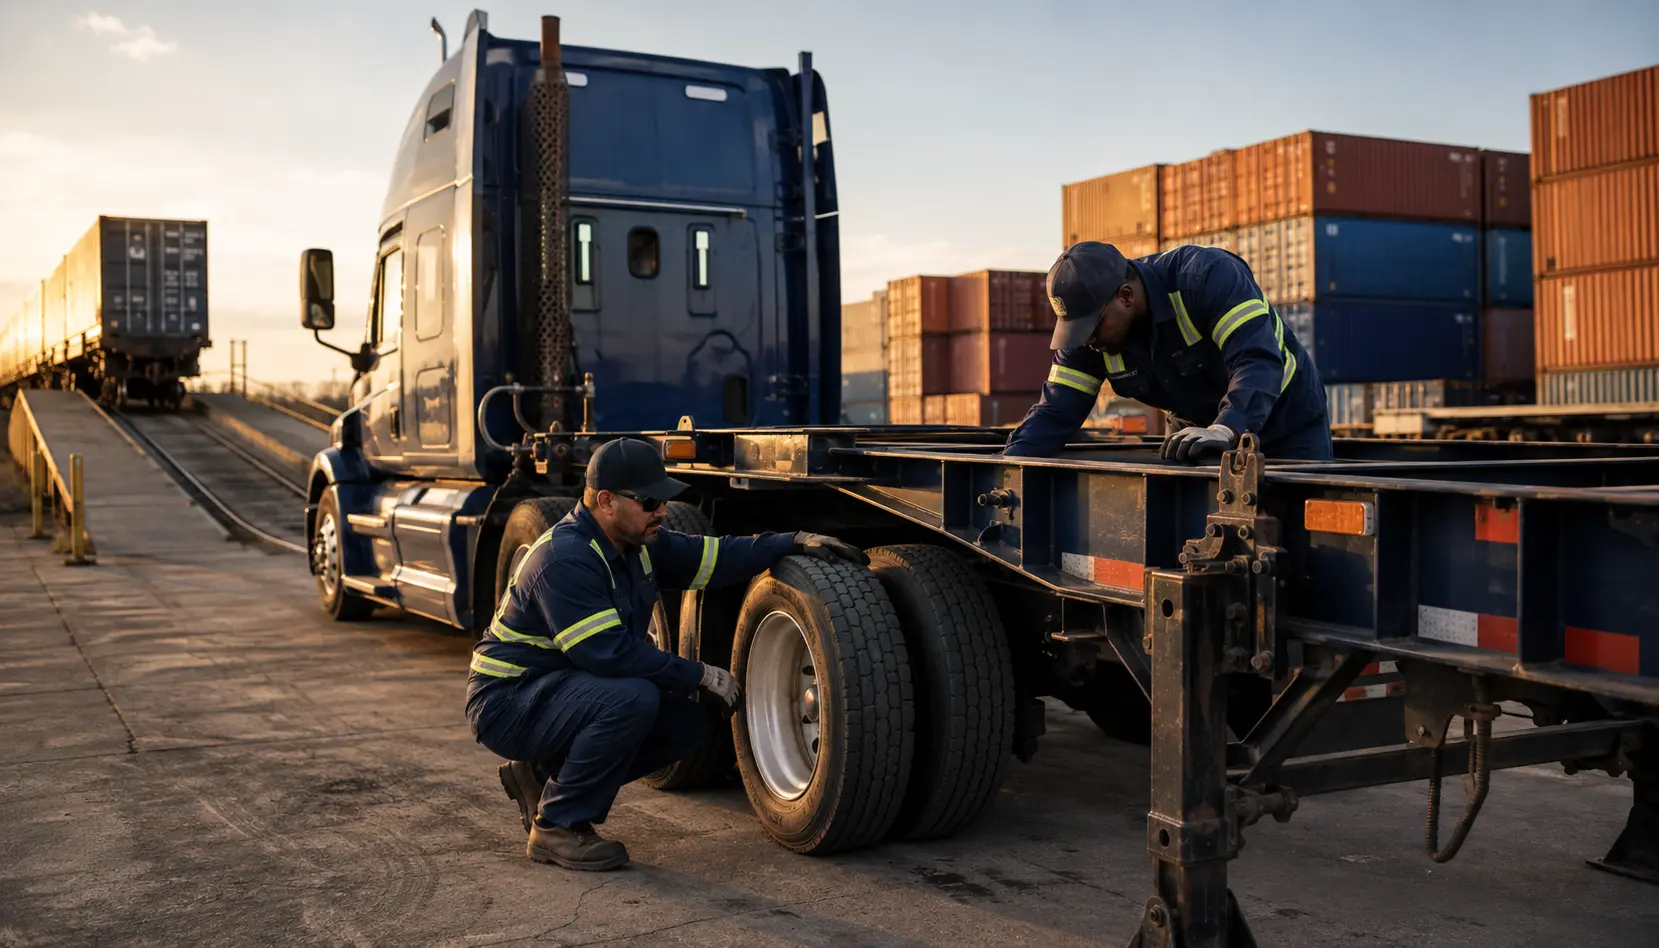
    Drayage team inspecting a container chassis and tires

    Chassis custody and inspection

    Interchange agreements, non-owned equipment values, inspection practices, maintenance and securement affect the coverage discussion.

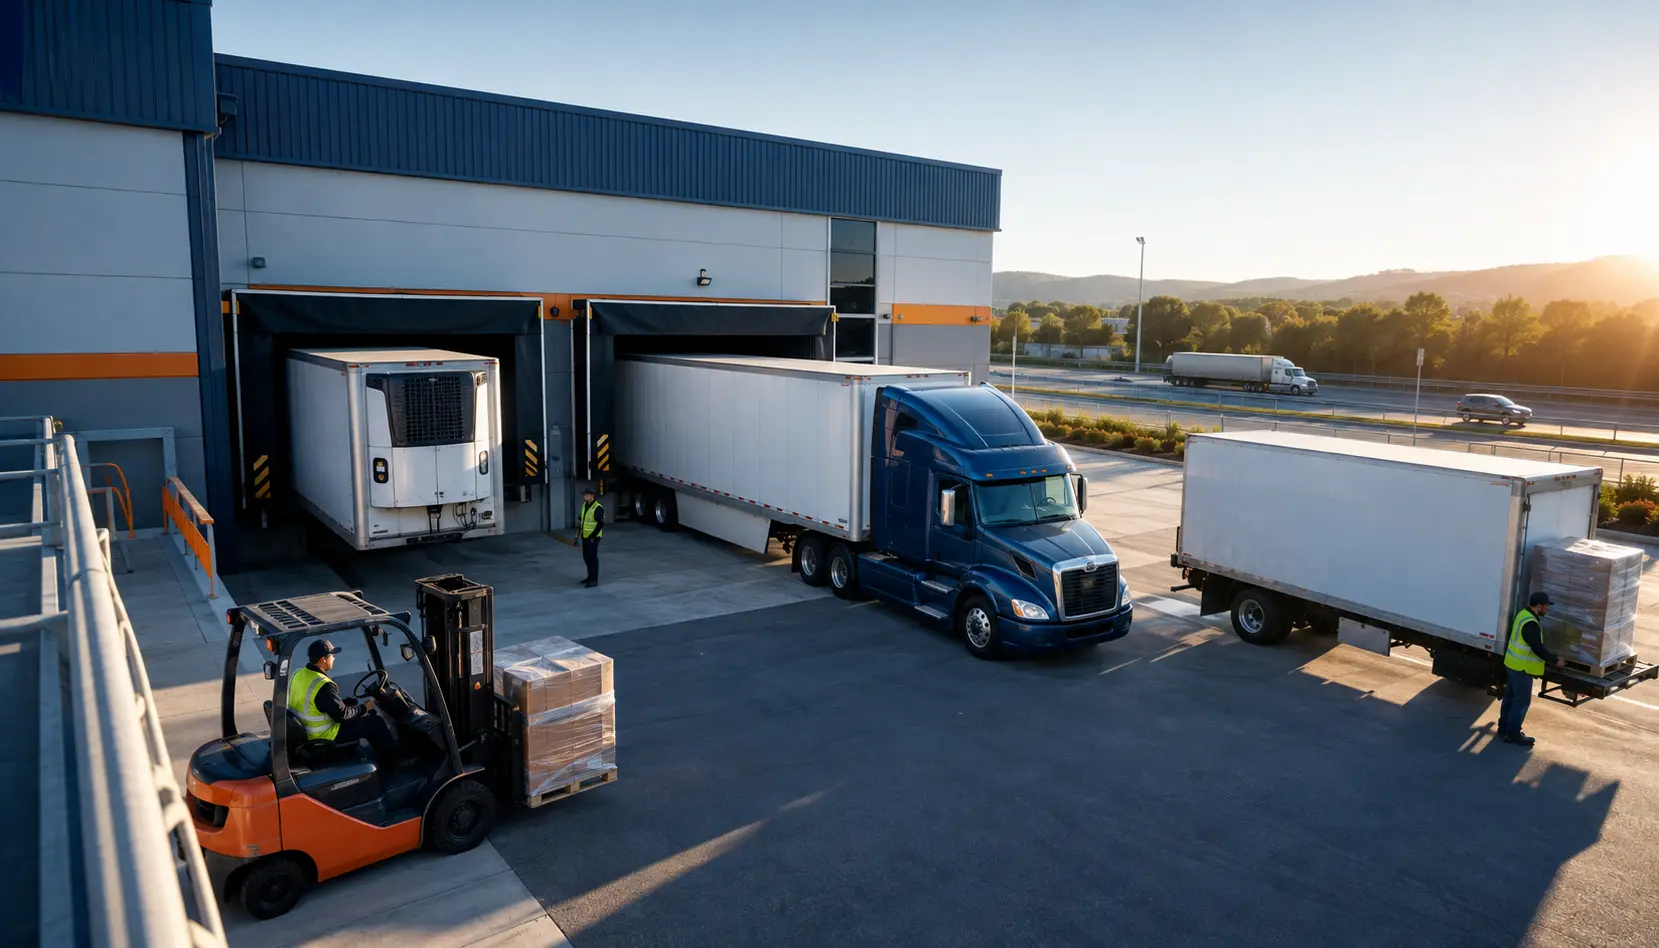
    Trucks and workers handling freight at a distribution warehouse

    Warehouse and delivery exposure

    Cargo handling, loading, refrigeration, delivery radius, customer mix and overnight parking complete the end-to-end risk picture.

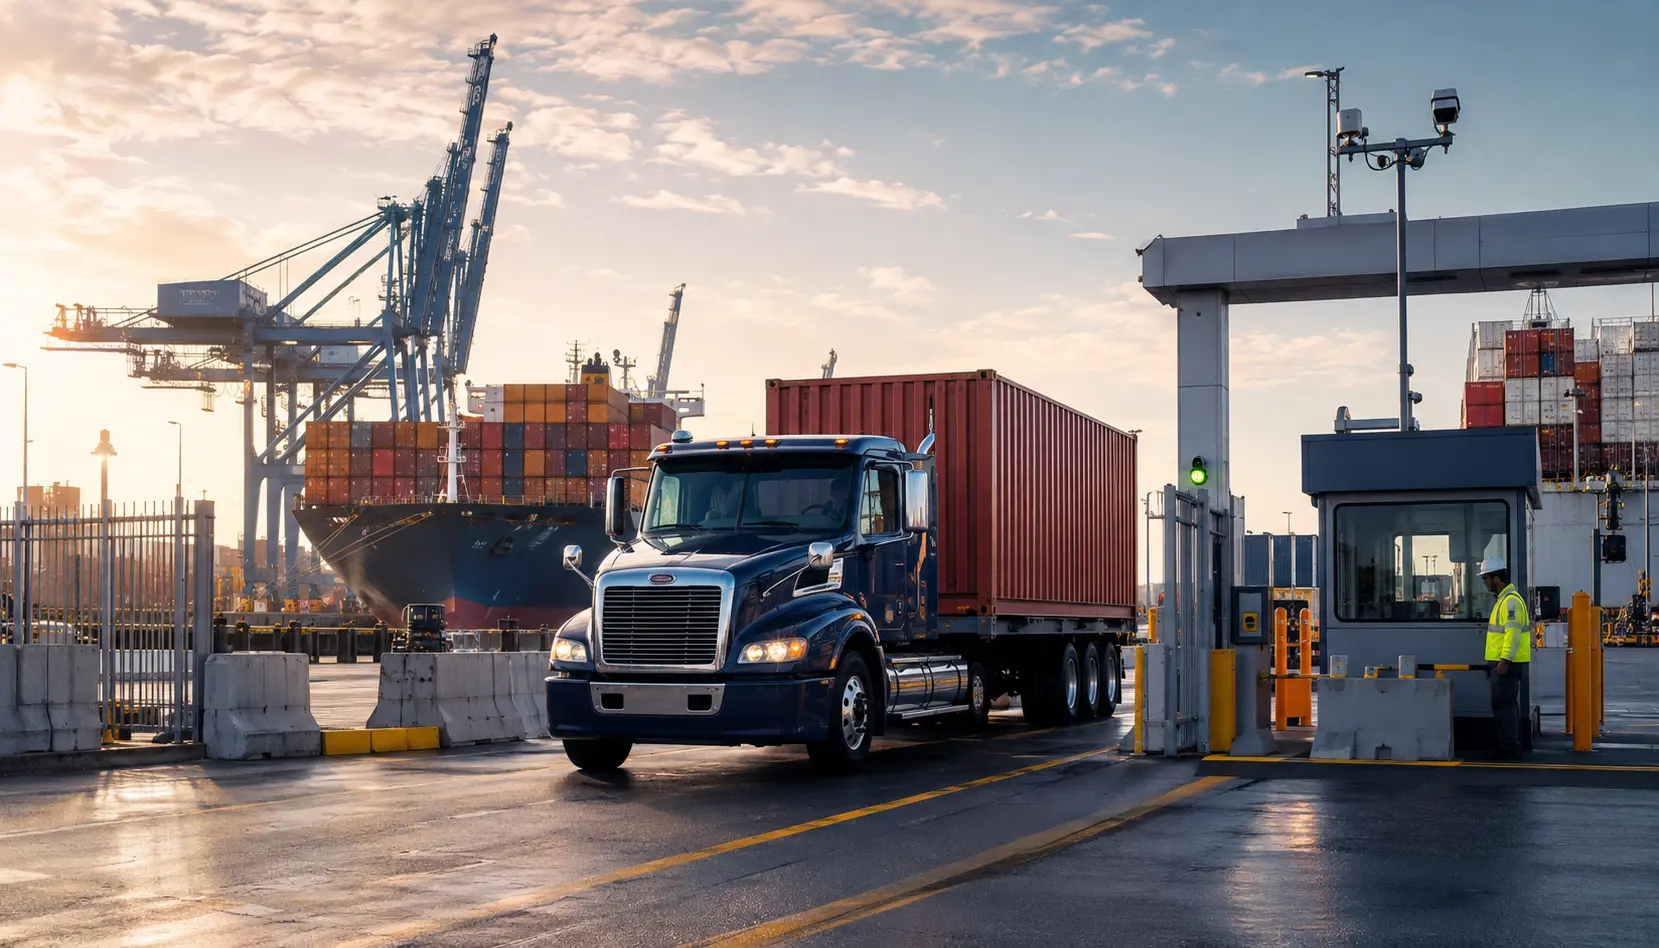
    Day-cab container truck entering a marine terminal gate

    Marine-terminal access

    Terminal access, credentials, gate activity, appointments, container volume and contract requirements belong in the operating profile.

    Quote comparison and renewal discipline

    Compare proposals on the same exposure basis and verify the named insured, vehicles, drivers, limits, deductibles, forms, endorsements, filings, payment terms, exclusions, and carrier conditions. Before renewal, reconcile schedules and operations, request loss runs early, document safety improvements, and address open claims or compliance issues.

    Truxsurance can help organize the insurance submission and review available market terms. Final eligibility, pricing, forms, coverage, filings, and timing remain subject to complete information, carrier underwriting, binding, and the issued policy.

    Intermodal port aerial view

    Get an Intermodal Quote for Fontana

    Same-day UIIA filings. E&S market access. Coverage that actually pays claims.

    Same-day indications available.

    Call Now